The Federal Government has introduced the Nigeria Presumptive Tax Regulations, 2026, empowering tax authorities to examine citizens' lifestyles, assets, business locations, and financial transactions to determine tax liabilities when reliable financial records are unavailable.
Published in the Federal Government’s Official Gazette on May 13, 2026, and retroactively taking effect from January 1, 2026, the framework stems from Section 29 of the Nigeria Tax Act, 2025. It aims to capture unrecorded income within the informal economy while incorporating strict safeguards for small-scale operators.
How Lifestyle and Asset Assessments Work
Under Regulation 10(2), revenue agencies can utilize a combination of indicators to estimate a taxpayer's actual business turnover if proper books are not kept:
Lifestyle & Assets: Evaluated alongside business locations and social associations.
While these indicators can support assessments where formal records are absent, authorities clarified that owning expensive assets does not automatically trigger taxation.
Taxpayers retain the full legal right to formally challenge assessments they deem inaccurate or excessive.
Exemptions and Tax Rates for Businesses
The regulations establish clear thresholds to protect small businesses and micro-traders>
The ₦12 Million Threshold: Businesses with an actual or estimated annual turnover not exceeding ₦12 million are entirely exempt from the presumptive income tax.
Businesses exceeding the ₦12 million mark are assessed at 1% of their annual turnover. For instance, a business generating ₦20 million annually would face a presumptive tax liability of ₦200,000. Where only daily sales figures exist, revenue agencies can estimate annual turnover using a maximum of 300 working days.
Relief for Informal Traders and Micro-Operators
Several categories of small-scale informal businesses are explicitly shielded from the levy. These include:
Akara, roasted yam, and plantain vendors
Groundnut and sachet water hawkers
Mobile barbers, manual tailors, and local cobblers
Newspaper vendors, wheelbarrow pushers, and roadside car washers
Phone-charging operators and small-scale garri processors
Eligible operators can obtain free exemption certificates or stickers from relevant tax authorities, valid for one year and renewable following verification.
Business News of Monday, 2 November 2026
Source: www.mynigeria.com
FG to use lifestyles, assets, and spending patterns to estimate undeclared business income
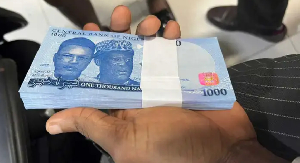 Authorities clarified that owning expensive assets does not automatically trigger taxation